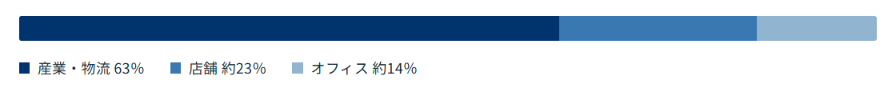
01 / U.S. Market
U.S. Market: Industrial and Logistics Drive Transactions
Total investment for the full year 2025 was $51.4 billion, a 16% increase year-on-year. The recovery continued in Q2 2026.[1][2]
Q2 2026 Transaction Volume by Property Type
*Approximate figures converted from CBRE published data. Totals may not match due to rounding.[2]
For single-tenant properties, there is a tendency for average cap rates to be lower as the remaining lease term increases. A survey as of mid-2026 showed approximately 7.4% for terms of 5 years or less, approximately 6.7% for 5–15 years, and approximately 5.9% for over 15 years. However, the term alone does not determine the price of an individual property.[3]
On September 16, the U.S. Federal Reserve raised its policy rate target range to 3.75–4.00%, an increase of 0.25 percentage points. Transactions and financial results for the first half of the year were based on figures prior to this decision, and it will be necessary to observe how long-term interest rates and funding costs are reflected in investment decisions in the second half of the year.[13]
How to Read This Report
"Net lease," "NNN," and "long-term lease" do not necessarily refer to the same scope. US market averages, acquisition yields of individual REITs, and Canada's all-property averages are calculated using different methodologies, so direct cross-comparison is avoided.
TRIPLE NETS - MARKET INSIGHT
The Current State of the North American Net Lease Market - Q2 2026
Unraveling the value of long-term lease real estate through U.S. transaction trends, the scale of specialized REITs and private equity firms, and case studies from Canada, Europe, and Australia.
Published September 23, 2026 | Triple Nets, Inc.
$12.8 billion
US net lease investment volume
2026 Q2, 13% increase year-on-year [2]
63%
Share of industrial and logistics facilities in US Q2 transaction volume [2]
Overview
Transactions are recovering. It is not just the length of the contract that determines valuation.
Investment in US net lease properties is estimated at over $144 billion in market capitalization for publicly traded net lease REITs, with investment volume in the second quarter of 2026 reaching $12.8 billion, a 13% increase year-on-year. While industrial and logistics facilities are driving transactions, investors are evaluating tenant creditworthiness, rent levels, expense burdens, and post-vacancy usability on a property-by-property basis. [2]
This article summarizes the current state of North American NNN (triple net) leases and specialized REITs based on published market statistics and corporate financial results. Drawing on examples from the UK and Australia, we consider how these can be applied to the structuring of commercial real estate in Japan.
Incidentally, the total market capitalization of J-REITs (58 constituents of the TSE REIT Index) was 15.5859 trillion yen as of August 31, 2026 (published by JPX), meaning that US net lease specialized REITs alone are approximately 1.46 times the size of the entire Japanese J-REIT market. Since J-REITs cover all sectors including office, residential, logistics, hotel, and retail, the US sector specialized in the single investment strategy of net leases exceeds that total.


02 / Market Scale
Recovery in transaction volume and expansion of assets under management
Transaction volume refers to the amount traded over a certain period, while total assets and AUM refer to the scale of holdings/management at each point in time. These are distinct metrics.
03 / Listed REITs
Operational Strategies of Net Lease REITs
Scale, tenant credit, contract duration, and asset composition. The factors emphasized by each company differ.
Sources & Research Scope
1. CBRE, 2025 Full-Year Net Lease Investment
2. CBRE, Q2 2026 U.S. Net Lease Market
3. Marcus & Millichap, 2026 Retail Market Mid-Year Survey
4. Realty Income, Q2 2026 Earnings
6. Agree Realty, Q2 2026 Earnings
7. Global Net Lease, Completion of Modiv Acquisition
8. Automotive Properties REIT, 2025 Annual Report
05 / Our Perspective
Structuring NNN leases in Japan
The North American experience highlights the importance of simultaneously evaluating rent income prospects and real estate value after tenant vacancy.
Even if expense burdens are defined in long-term contracts, if a tenant becomes insolvent, the owner retains the risk of expenses and re-leasing. Realty Income also discloses that there are cases where expenses cannot be recovered from tenants. [15]
-
Tenant creditworthiness and the operational importance of the location
-
Scope of burden for taxes, insurance, repairs, and CAPEX
-
Conditions for rent revision, early termination, guarantees, and re-leasing
-
Potential for repurposing and renovation costs after vacancy
Triple Nets Co., Ltd. connects land, tenants, and capital, combining NNN leases and BTS facility development according to the project. We examine contracts and development plans that suit the facility's use and the tenant's business, including retail/commercial facilities, logistics facilities, factories/manufacturing facilities, and healthcare facilities.
This is our business perspective based on publicly available information and does not guarantee individual investment results.
04 / Beyond North America
Canada, the UK, and Australia also have different forms of net lease markets
We examine the contract terms and investment markets of each country, distinguishing them from the US NNN model.
11. Charter Hall Long WALE REIT, FY2026 Financial Results
12. Blue Owl, European Fund Final Close
13. FRB, Statement on September 16, 2026
14. Bank of Canada, Statement on September 2, 2026
15. Realty Income, 2025 Annual Report
16. CBRE, 2024 Full Year Net Lease Investment
17. Realty Income, 2021 Annual Report (2020/2021)
18. Realty Income, 2023 Annual Report (2022/2023)
19. Realty Income, 2024 Annual Report
Realty Income
Diversification and Large-Scale Operations
15,588 properties as of the end of June 2026, with an occupancy rate of 98.8%. The 2026 investment plan has been increased from $9.5 billion to $10 billion. We are diversifying across numerous tenants and uses, and also utilizing private equity funds.[4]
NNN REIT
Single-tenant retail and long-term leases
3,774 properties, 99.1% occupancy rate. Q2 new investment volume was $291 million, initial cash cap rate on acquisitions was 7.3%, weighted average lease term is 17.9 years. [5]
Agree Realty
Retail tenant creditworthiness
2,825 properties, 99.8% occupancy rate. Investment-grade retail tenants account for 65.8% of annualized base rent. Also holds ground leases. [6]
Global Net Lease
Shift to industrial
After the acquisition of Modiv Industrial, the industrial portion of straight-line rent reached approximately 50%. An example of the move to rebalance the portfolio composition. [7]
*The 7.3% for NNN REIT is a yield based on initial cash rent for newly acquired properties. The scope and calculation method differ from the U.S. market average of 6.9% mentioned above.[5]
*Aggregating transaction amounts does not equal the total outstanding balance of the entire market. REIT total assets and AUM of asset management companies also fluctuate due to valuations, sales, and corporate acquisitions, and are not figures representing the market size of the same population.

*The average cap rate for all uses in Canada in Q2 2026 is 6.58%. This is not a value specific to NNN. The Bank of Canada held its policy interest rate at 2.25% on September 2.[9][14]
TRIPLE NETS
Exploring the potential of commercial real estate through concrete projects.
We welcome inquiries from land owners, brokerage firms, tenant companies, operating companies, financial institutions, and investors regarding NNN leases, BTS facility development, and corporate real estate sale-and-leasebacks.
$144 Billion
Market Capitalization of U.S. Publicly Traded Net Lease REITs
*This article is a general market commentary based on publicly available information as of September 23, 2026. Market statistics are defined differently by various research firms, and this does not constitute a solicitation for individual investment or a guarantee of future returns.
